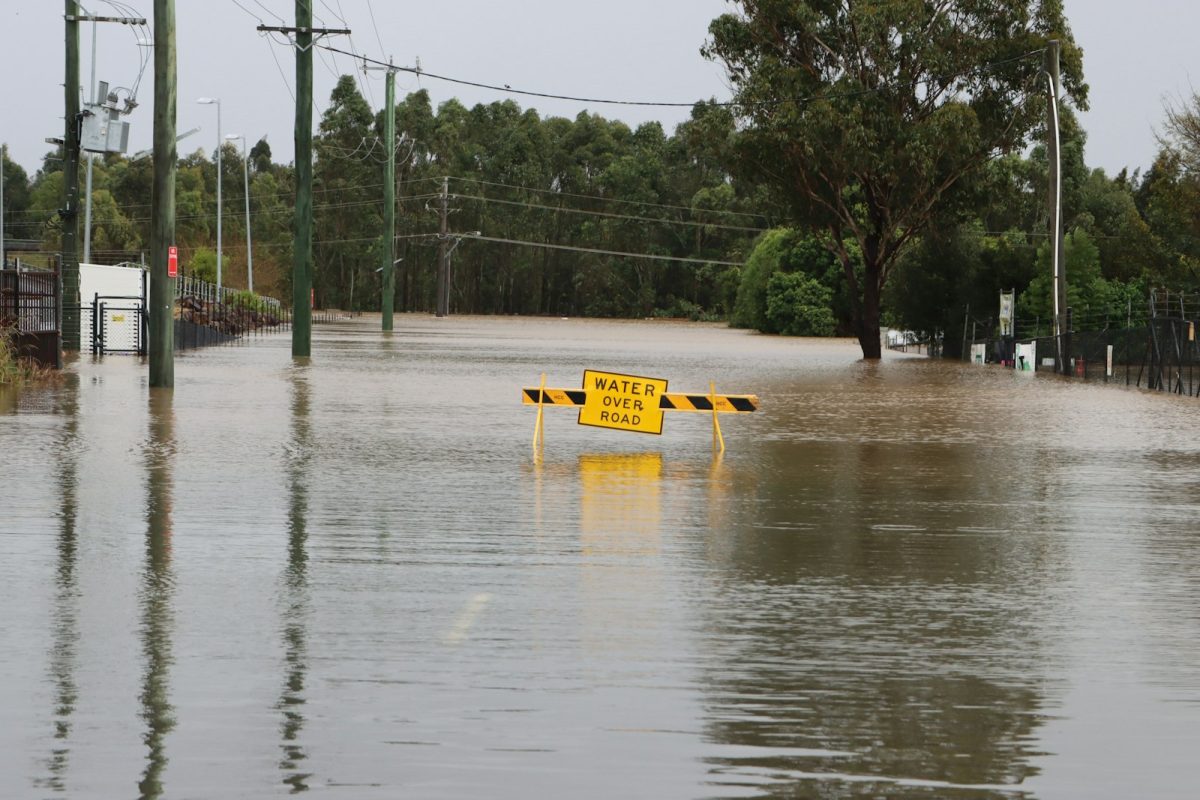
Floods are among the most common natural disasters, yet standard home policies exclude them. Separate coverage fills the gap.
Key facts
- Standard homeowners and renters policies don’t cover flood damage.
- Flood insurance is available through the National Flood Insurance Program (NFIP) and private insurers.
- NFIP policies usually have a 30-day waiting period before coverage starts.
- Homes outside high-risk zones can still flood, so coverage is worth considering broadly.
Flooding can happen almost anywhere, from heavy rain, snowmelt, storm surge or overwhelmed drainage. Standard homeowners policies exclude it, so protection needs a separate policy.
Where flood insurance comes from
| Source | What to know |
|---|---|
| National Flood Insurance Program (NFIP) | Federal program sold through insurers and agents; standard coverage limits |
| Private flood insurance | May offer higher limits or extra coverage; availability varies |
Key NFIP features
- Building coverage: up to $250,000 for a home.
- Contents coverage: up to $100,000, bought separately.
- Waiting period: usually 30 days before a new policy takes effect, with some exceptions, such as when coverage is required for a new mortgage.
Risk to know
Don’t wait for a storm forecast to buy flood insurance. Because of the usual 30-day waiting period, a policy bought when a storm is approaching typically won’t cover it.
Who should consider it
- homeowners in high-risk flood zones, where lenders often require it
- homeowners in moderate- or low-risk areas, where flooding still happens
- renters who want to protect their belongings
Smart tip
Look up your property’s flood risk on FEMA’s flood maps, and ask an agent for quotes from both NFIP and private insurers.
Filling the gap
Flood coverage complements your homeowners policy rather than replacing it. Check how each policy values damaged belongings, as explained in our guide to replacement cost vs. actual cash value, and keep your home inventory up to date.
Questions we hear
How much coverage does NFIP offer?
For homes, NFIP coverage goes up to $250,000 for the building and $100,000 for contents. Private policies may offer more.
Is flood insurance required?
If you have a federally backed mortgage on a home in a high-risk flood zone, your lender will usually require it.
Do renters need flood insurance?
Renters can buy contents-only flood coverage to protect their belongings.
This guide is general information, not insurance or legal advice. Coverage, prices and rules vary by insurer and by state, so read your policy documents and check with your insurer, a licensed agent or your state’s department of insurance before you decide.